I have been a personal finance coach for nearly 10 years and only recently started getting messages like this:
“I can’t believe i spent $6K on [redacted course] and it was whoa expensive… You gave us specific advice that felt genuine and not generic”
“I wish I would of got your service instead of [the same course as above]. I can’t change the past or dwell on it but take it as a lesson.”
So I began asking around and gathering what online creators charged (thanks ChatGPT). And while not all creators are like this, the numbers were eye watering.
- Robert Kiyosaki of the Rich Dad Poor Dad (which was a half decent book) sold an elite membership that started at $20K. I think my book is better researched and not based on a made up character.
- A female personal finance coach pushed a $1000+ course and a $5000+ program. And that’s how she boasts of making 6 figures a month. Clo Bare Money Coach
- An online fitness program wanted to charge my follower $5K for 6 months… And while I could see why they priced that way, honestly, an in person fitness trainer already costs less than that.
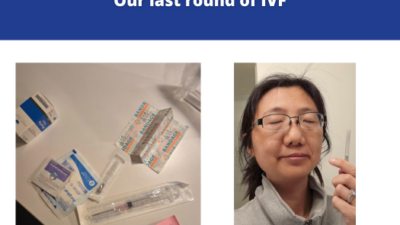
- A fertility coach fleeced a follower of mine, who had failed IVF three times, for $8K, to sell some vitamins.
- A very well known personal finance personality who seemingly only wants to work with people making $100K or more… The $6K mentioned above in the emails I got. The Budget Dog
- $697 a year for a personal finance app from a social worker turned personal finance creator, which infuriated the social worker follower who mentioned it to me.
For all the gripes that people have about Dave Ramsey, at least Financial Peace University is still below $200.
Don’t get me started on the financial advising industry which takes 1% of your portfolio regardless of performance.

As a personal finance coach who does charge, I do it because charging gets people to do things. And I charged because I felt it would help keep the rising tide afloat of everyone else who is trying to make a living on the internet.
Based on my initial research four years ago, I held my courses to at the $200-300 mark, and my coaching has not crossed $2000.
When I coach someone, I am investing minimum 5-7 hrs into working with them 1:1. I am not running it through some software and cranking it out.
I only recently found out I am on the lower cost end. But man, I’m wearing that with pride.
And, not all personal finance creators charge this much. Some have very reasonable services, but also are sponsored by very high-paying brands like SoFi, crypto companies, to make up the difference.
Now I am mostly just pissed off at the industry.

As someone who doesn’t need your money, here is my blueprint for you to get wealthy, and where I think you can largely replicate what I do, and where I think paying makes sense and for how much
1. Read books. You can check out my own book, request your local library to carry it, or read any of the other excellent books on my book list. This is how I got started and most of the books can be had for free if you’re willing to wait at the library.

2. Yes, follow online content for free. Back in the old days (gosh I feel old now) it was blogs. My personal favorites were Get Rich Slowly and Mr. Money Mustache. They made money by running ads on their blogs and I didn’t mind. And you know why their content is still solid? Because they stopped writing. They achieved the personal finance independence they wanted and stopped caring. I’m on Instagram as @savemycents
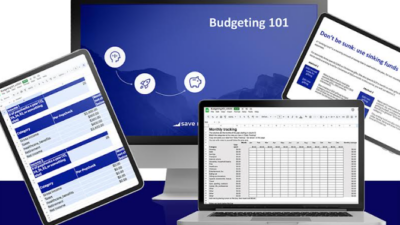
3. Buy a budgeting template of some sort. I was learning to get good at financial modeling with excel at work and so made my own (and eventually it evolved into the forecast model I use now for private coaching). However, there are many budgeting templates available out there as well as software. I personally use Money by Microsoft which is sadly defunct and so hubby and I hobble off of an old version of it, and unless you all know how to make old install files work, I don’t recommend it. For beginners, I would happily recommend my own template which you can get inside The Wealth Club (first month free). Or you can pay for apps like Monarch Money, Copilot Money, and You Need a Budget
4. Pay for a very basic investing course. It shouldn’t cost more than $500. I spent $250 on a flat fee advisor in my 20s and then learned investing from having gathered knowledge through my economics classes at Harvard, and also, through my first employer because I had to learn how to navigate a Bloomberg terminal.
All-in, getting comfortable with not only investing but also navigating the complex US retirement landscape, probably took me a good 5 years, and looking back I designed my class because I felt silly I spent a good 5 years trying to learn everything. If you want a crash course, then I think it’s worth a few hundred dollars to do so, you can try my Save My Retirement Masterclass – use the code BLOG250 to get it for $250.
Sometimes I run even better sales, but I put it on sale when I have the energy to do a sale – it’s tied to my own schedule. Also, feel free to check out my free investing guide.
And the other one that I’d recommend is by my friend Jeremy at Personal Finance Club. His cost less than mine and I’ve verified with friends that he covers less material as well. But I recommend him all the same because he, too, is genuine and doesn’t need your money, and heck, I’m not getting any commission off of that link either.
4. Use a robo advisor to get you an allocation for your investing portfolio. This can be done for next to nothing. Do not go to a financial advisor who starts by charging 1% of your assets. I tell most people that they can try something like Fidelity Go, Schwab automated investing. I tried Betterment myself. Or heck, ask chat / AI or just Google. I began my investing with googling. And while I still laugh to this date that I once picked an investment because I liked the name… Well, it worked out.
5. Many of your money issues have nothing to do with math, calculators, or budgeting, but rather, with your mental health and mindset. If you’re curious what this means, welcome, you’re at the right place. If you’ve cycled in and out of debt, that’s why I am here. If you cannot stop spending money it feels like a addiction. That’s why you should read my blog and content. If you are scared to death of money or thinking about it, I can help you do things scared.
That’s what I write about – the psychology that keeps people stuck and in poverty or unable to cycle out of debt. Follow my content on Instagram and YouTube for free to hear more about this, and also check out my book, Wealth Is a Mindset. Get one month’s free admission into The Wealth Club.
Maybe in a few years you’ll also want to be coached by me and I promise you, I won’t be fleecing you, because I don’t need your money.
And heck, if I get big enough I’ll hire other coaches willing to do it at the same reasonable price too.
It’s still a fine living, just isn’t gonna pay for business class flights or Jimmy Choo shoes full price. That’s what I have my investments for.